A premarket breakout backtest can validate a real, tradable edge, but only when you filter for relative volume and put every result through walk-forward and slippage stress tests first. Raw opening-range breakouts, tested without a volume filter, often perform close to a coin flip. The factor that separates a durable system from a curve-fit fantasy is almost always relative volume (RVOL) combined with disciplined symbol pre-selection. The rest of this guide walks you through the exact backtest design step by step, including how to run it inside Trade4.
TL;DR:
- Using relative volume filters, especially 1.2 times RVOL or higher, significantly improves the reliability of premarket breakout backtests over unfiltered strategies.
- Proper symbol selection before the open, based on volume, gaps, float, and news, is crucial to avoid lookahead bias and skewed results.
- Incorporating slippage, commission, and risk management into backtests ensures more realistic performance estimates, with stress testing revealing strategy fragility.
- Walk-forward validation and parameter sweeps differentiate truly robust strategies from overfit models that only perform well in specific historical windows.
- Trade4's platform supports tick-level testing, visual rule building, and stress testing, enabling traders to develop valid, live-ready premarket breakout strategies without coding.
Table of Contents
- What Do Premarket Breakout Backtests Typically Show?
- What Counts as a Premarket Breakout vs. an Opening-Range Breakout?
- How Do You Design a Backtest That Won't Lie to You?
- How Do You Actually Run a Premarket Breakout Backtest Step by Step?
- Which Filters Actually Change Backtest Outcomes?
- How Do You Read the Results Without Fooling Yourself?
- Why Trade4 Is Built for This Exact Backtest
- The Honest Take on Backtesting Premarket Breakouts
- Ready to Run Your Own Premarket Breakout Backtest?
- Sources Worth Reading Next
What Do Premarket Breakout Backtests Typically Show?
Backtest results for opening-range and premarket breakout systems split into two camps: strategies that filter aggressively and strategies that don't. The gap between the two is not small.
Large mechanical tests of the popular "opening range plus retest" scalp, run across many simulated trades on hundreds of stocks, produced a win rate that reflected near-random outcomes without an apparent edge. It's a pattern that, without added conditions, behaves close to random noise across most market conditions.
The gap between those two outcomes comes down to filtering and rule discipline, not luck.
Follow-through rates also vary by symbol. In a small sample, some high-momentum names showed higher follow-through on upside breaks compared to broader index proxies, illustrating the importance of symbol selection.
A few things to keep in mind before trusting any single number:
- Published "strong" results are frequently drawn from a narrow symbol list or a bull-market window, which inflates the apparent edge.
- Long setups and short setups do not perform symmetrically. Short breakout failures tend to cluster in high-volatility, risk-off regimes, while long breakouts thrive in trending, low-VIX stretches.
- A 50% win rate paired with a healthy profit factor beats a 65% win rate with poor risk-to-reward, every time.
Statistic Callout: A 10-year walk-forward validated ORB system produced a 50.3% win rate and a Sharpe ratio of 2.47 across 4,292 trades, surviving 3x slippage stress. A naive retest-scalp variant tested across 165,336 trades landed near 32.6%. Same pattern family, wildly different outcomes, because of filtering.
What Counts as a Premarket Breakout vs. an Opening-Range Breakout?
These terms get used interchangeably in trading forums, and that sloppiness ruins backtests before they start. If your entry logic doesn't match the definition you think you're testing, your results won't mean what you think they mean.
Premarket breakout setups trigger on price action during the premarket session, typically 4:00 AM to 9:30 AM Eastern, when a stock breaks above its premarket high or a defined resistance level formed before the opening bell. Opening-range breakout (ORB) setups wait for the regular session to begin and use the high and low of a defined window after 9:30 AM, commonly 5, 15, 20, or 60 minutes, as the breakout trigger.
The most common variants you'll see in published tests and in retail trading strategies include:
- Gap-and-go: a premarket gap (often 4% or more from the prior close) combined with an opening-range breakout confirmation once the regular session starts.
- ORB immediate entry: buy the instant price ticks above the range high, no confirmation candle required.
- ORB retest entry: wait for price to break the range, pull back to retest it, and enter only if that retest holds.
- VWAP or index confirmation: require price to also be above VWAP, or require a correlated index (like SPY or QQQ) to be trending the same direction, before triggering the trade.
These choices are not cosmetic. Immediate-entry rules generate far more trade signals and lower average win rates. Retest rules cut trade count sharply and, counterintuitively, sometimes hurt expectancy rather than helping it, because you're entering later at a worse price after the move has already partially played out. Whichever variant you test, define the exact time window and entry trigger in writing before you run a single trade. "Around the open" is not a backtest rule.
How Do You Design a Backtest That Won't Lie to You?
Most amateur premarket breakout backtests fail not because the strategy idea is bad, but because the test itself has a leak. Get the design right before you touch entry and exit logic.
1. Choose your bar size and history length deliberately. One-minute bars are the practical floor for most premarket and opening-range work; they capture enough granularity to time entries without the noise and file size of tick or one-second data. Reserve 1-second or tick-level granularity for validating fill assumptions on your highest-conviction setups, not for routine parameter sweeps. For history length, aim for at least three to five years across multiple volatility regimes. A backtest built entirely on a single trending bull year will look great and fail live.
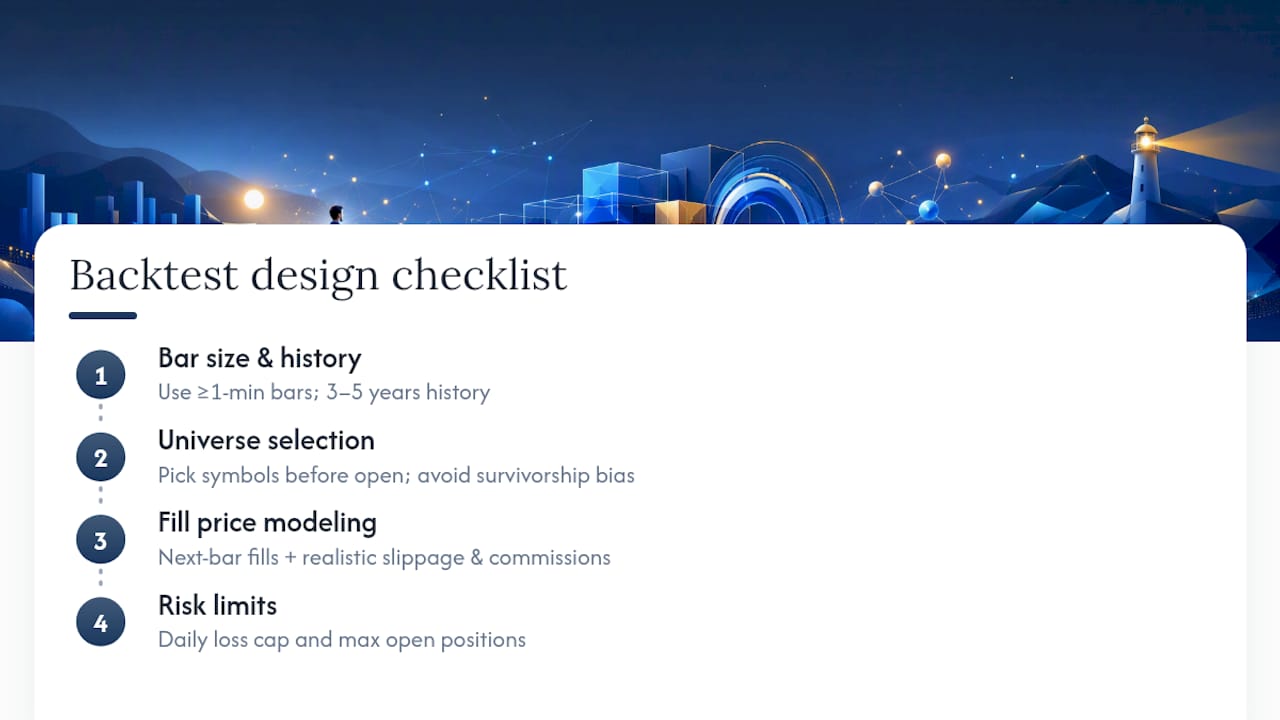
2. Select your universe before the bell, not after. This is where lookahead bias sneaks in undetected. If your backtest scans for "the biggest premarket gappers" using data available only after the session closed, you've built a test that knows the future. A defensible test defines symbol selection criteria using only information available before 9:30 AM: premarket volume relative to a trailing average, gap percentage from prior close, float size, and news catalysts tagged before the open. Survivorship bias matters here too. If your data feed drops delisted or halted tickers, your universe silently skews toward past winners.
3. Model your fills honestly. Assume next-bar fills, not fills at the exact breakout price. If your signal triggers on the 1-minute bar close, you fill on the next bar's open, plus slippage. Bake in a per-trade commission and a slippage assumption that reflects premarket and early-session spreads, which run wider than midday liquidity. Fixed-dollar risk per trade, rather than a percent of equity, tends to better reflect how small-cap intraday traders actually size positions and makes your sensitivity to slippage easy to see in the results.
4. Set a daily loss limit and a max position count. Real trading has a stop-the-bleeding rule. A backtest without one will happily let a losing streak compound into a drawdown you'd never accept live.
Pro Tip: Run the same backtest twice: once with your realistic slippage assumption, and once with zero slippage. If the strategy's edge disappears under realistic costs, you've found a strategy that only works on paper. That comparison takes five minutes and saves you months of live losses.
How Do You Actually Run a Premarket Breakout Backtest Step by Step?
Here's the sequence to follow, whether you're using Trade4 or building your own scripts.
1. Prep your data and timeline. Pull one-minute (or tick, if your platform supports it) historical price and volume data for your target universe. Define your opening-range window explicitly, say, the first 15 minutes after 9:30 AM. Compute relative volume (RVOL) for each candidate symbol using a trailing 20 or 30 day average volume at the same time of day.
2. Write your entry signal as explicit boolean logic. Don't leave anything to interpretation.
3. Define your stop, target, and trade validity window. A common structure: stop below the opening-range low (or a fixed dollar/percent risk), target at a fixed risk-multiple (1.5R to 3R is typical for ORB systems), and a hard time-based exit if neither level is hit by a set cutoff, often the close or early afternoon. Set your fill assumptions here too: next-bar open fill, plus your slippage estimate from the design phase.
4. Run the initial in-sample test. This first pass tells you whether the logic even produces a plausible number of trades and a coherent equity curve. Don't trust this result yet. It's diagnostic, not conclusive.
5. Run walk-forward and out-of-sample validation. Split your history into sequential windows, optimize parameters on one window, and test on the next unseen window, then roll forward. This is the single biggest separator between a strategy that will survive contact with live markets and one that was quietly curve-fit to a specific stretch of history.
6. Run a parameter sweep. Test your RVOL threshold, stop distance, and time windows across a reasonable range, not just your favorite numbers. If small changes to a parameter blow up your results, that parameter is probably overfit rather than meaningful.
7. Stress test the survivors. Three checks matter most:
- Triple your assumed slippage and rerun the test. If profitability survives, that's a good sign.
- Remove your top 5 to 10 winning trades and rerun. If the entire edge came from a handful of outlier trades, you don't have a system, you have a lottery ticket.
- Run a Monte Carlo resampling of trade order. This randomizes the sequence of your wins and losses to show you a range of plausible drawdown paths, not just the one path your specific historical sequence happened to produce.
8. Check same-day re-entry behavior. If your system allows multiple entries per symbol per day, verify whether the apparent edge depends on repeated intraday re-entries. That behavior can multiply transaction costs and slippage in live execution in ways a simple backtest summary won't show you.
Each of these steps builds a case file. By the time you've run all eight, you should have either a strategy worth risking real capital on, or clear evidence of exactly why it isn't ready yet. Both outcomes are useful. Only one of them is expensive to discover live instead of in a backtest.
Which Filters Actually Change Backtest Outcomes?
Not every filter earns its place in a ruleset. Some transform a coin-flip pattern into a real edge. Others just add complexity without improving results, or actively hurt them.
Relative volume is the filter that matters most. Across multiple independent tests, adding an RVOL threshold, commonly requiring the breakout bar to run at 1.2x or higher relative volume, consistently improved outcomes compared to no filter at all. This makes intuitive sense: a breakout on thin volume is noise, while a breakout backed by real participation reflects actual institutional or momentum-driven buying pressure.
Symbol pre-selection matters nearly as much. Set your criteria before the bell: minimum premarket dollar volume, a gap percentage threshold, adequate float size for clean execution, and ideally a news catalyst tag. Stocks in the top quartile of premarket volume relative to their own history tend to produce cleaner, more tradable breakouts than the broader universe.
Statistic Callout: Adding an RVOL threshold around 1.2x on the breakout bar has repeatedly turned a near-coin-flip opening-range pattern into a filtered setup with materially better expectancy, based on multiple independent backtest reviews. The filter is doing more work than the entry trigger itself.
The robustness checks worth trusting are the ones that stress the strategy rather than flatter it:
- Walk-forward validation across rolling time windows, not a single in-sample optimization.
- Half-split testing, where you validate the first half of history independently against the second.
- Removing top trades to see if the edge survives without its best outliers.
- 3x slippage stress tests to confirm the edge isn't a fragile artifact of unrealistically tight fills.
- Monte Carlo resampling of trade order to map the real range of drawdown outcomes.
One counterintuitive finding worth flagging: overly strict retest confirmation rules, like waiting for a clear rejection candle before entering, frequently backtest worse than looser triggers. Waiting for that confirmation means entering later, at a worse price, with a wider effective stop. The pattern recognition feels safer. The numbers often say otherwise.
How Do You Read the Results Without Fooling Yourself?
A backtest report full of green numbers doesn't mean much until you know which numbers actually predict live performance and which ones are decoration.
Expectancy (average dollar result per trade, accounting for both wins and losses) is the single number that tells you whether the system has a real statistical edge once size and frequency are held constant.
Match the drawdown profile to what you can genuinely tolerate without abandoning the system mid-drawdown.
Watch for these traps before you scale up:
- Small trade counts (under a few hundred) produce metrics that look convincing but carry huge statistical uncertainty.
- A strategy tested only in a single volatility regime, all bull market or all high-VIX, won't tell you how it behaves when conditions shift.
- Premarket fills are genuinely harder to get than regular-session fills; thin books mean wider spreads and a higher chance of partial fills, especially on lower-float names.
- Market or limit order choice matters more in premarket hours than midday, since a market order into a thin book can slip several ticks past your intended entry.
Pro Tip: Size every backtest's "typical" trade using your worst-case realistic fill, not your best-case one. If the strategy still clears a reasonable profit factor after that haircut, you're looking at a number you can actually trust going live.
Why Trade4 Is Built for This Exact Backtest
Everything described above, tick-level fill accuracy, RVOL-based filtering, walk-forward validation, and slippage stress testing, maps directly onto features inside Trade4's no-code backtester. The platform runs on historical data down to one-second granularity, so you can move from a 1-minute prototype to a tick-accurate fill check without switching tools or rebuilding your logic from scratch.
Trade4's visual pattern builder lets you define opening-range windows, RVOL thresholds, and time-valid entry logic without writing code, and its event-driven engine applies next-bar fills with your specified slippage and commission assumptions automatically. Same-day re-entry analytics flag whether your apparent edge depends on repeated intraday entries that would compound transaction costs in live trading, exactly the check recommended in the step-by-step process above.
Parameter sweeps and walk-forward runs export as reproducible reports, so you can rerun a stress test months later and confirm nothing has quietly changed in your assumptions.
The Honest Take on Backtesting Premarket Breakouts
Most retail breakout strategies you'll see promoted online were never walk-forward tested, never stress-tested against slippage, and never checked for whether their edge depended on five lucky trades. That's not a minor oversight. It's the difference between a strategy and a story someone told themselves after a good month.
Keep it in the notebook when it hasn't.
Before you risk real capital, rehearse the execution mechanically: paper trade the exact ruleset for at least a few weeks, watching specifically for the moments where your emotions want to override the signal. That gap between backtested discipline and live-trade impulse is where most edges actually die. Ramp position size slowly once live results start tracking your backtest's expectancy, not before.
— Romans
Ready to Run Your Own Premarket Breakout Backtest?
Reading about walk-forward validation and RVOL filters only gets you so far. Trade4 gives you a no-code way to actually build and stress-test the exact rules covered here, without writing a line of backtesting code or managing a local database of tick data.

With Trade4, you can:
- Build opening-range and gap-and-go entry logic visually, with RVOL and time-window filters baked in.
- Run tick-to-1-second granularity fills to test realistic slippage assumptions, not optimistic ones.
- Use same-day re-entry analytics to check whether your edge depends on repeated intraday entries.
- Export walk-forward and Monte Carlo stress-test reports you can rerun as market conditions shift.
If you want a broader strategy foundation alongside your intraday breakout work, Profitomics' swing trading and compounding resources offer a useful complementary perspective for traders building a full system beyond the opening bell.
Start with the Trade4 getting-started guide to load a sample ORB template and run your first walk-forward test this week. If you want to see current plan limits on data history and job queue size before committing, check the Trade4 pricing page.
Sources Worth Reading Next
The step-by-step backtesting guide on the Trade4 blog expands on the methodology covered here with additional worked examples. For small-cap traders testing gap-driven setups specifically, the gap short strategy backtest breakdown covers metrics and pitfalls unique to short-side small-cap gaps. The broader Trade4 blog archive collects ongoing tutorials on filtering, robustness testing, and reading backtest reports without fooling yourself.